
What Are Seller Concessions in Real Estate?
Seller concessions in real estate refer to the closing costs, repair credits, or administrative fees that a seller agrees to pay on behalf of the buyer. These financial contributions lower the buyer's immediate out-of-pocket expenses required to close the loan, effectively facilitating a smoother, faster real estate transaction.
Why Would a Seller Consider Concessions?
A seller considers concessions when the potential benefits of helping a buyer outweigh the cost of providing that assistance. The right approach depends on your property's condition, local competition, and the strength of the offer.
Closing the Deal Faster
Buyers must account for more than their down payment. Lender fees, title expenses, prepaid insurance, and initial escrow deposits can add significantly to the cash needed at closing.
Offering to cover some eligible expenses may help a qualified buyer move forward without exhausting their available funds. It can also differentiate your home from similar listings that offer no financial flexibility.
Atlanta's market conditions make this strategy worth considering. According to Atlanta REALTORS®' September 2026 Market Brief, Metro Atlanta recorded 3,680 home sales, down 18.5% year over year. Active listings increased 6.7% to 21,053, while homes averaged 30 days on the market.
These figures cover an 11-county Metro Atlanta area. They do not mean every neighborhood faces the same conditions, but they illustrate why some sellers may benefit from considering well-structured offers rather than focusing exclusively on price.
Offsetting Repair Requests
A home inspection may uncover an aging HVAC system, minor plumbing concerns, roof wear, or other maintenance issues. You can negotiate repairs, agree to an appropriate credit when permitted, or decline the request and negotiate other terms.
A repair credit can be convenient when arranging contractors would delay closing or require you to manage work before moving. The buyer gains flexibility to organize repairs after taking ownership, while you avoid coordinating the work yourself.
However, not every problem should be handled with a credit. Significant structural damage, safety concerns, or issues affecting insurability may require further evaluation. Discuss the findings with your agent and appropriate professionals before deciding how to respond.
Evaluating Atlanta Real Estate Offers
The Impact on Your Bottom Line
When comparing Atlanta real estate offers, look beyond the headline purchase price. A higher offer with substantial concessions may leave you with less money than a lower offer with fewer requested expenses.
Consider two hypothetical offers on your home:
- Offer A: $500,000 purchase price with $10,000 in seller concessions.
- Offer B: $492,000 purchase price with no seller concessions.
Offer A produces $490,000 after the stated concession, while Offer B produces $492,000. Before accounting for other costs and contract terms, Offer B leaves you $2,000 ahead.
Your actual net proceeds will also depend on mortgage payoff, brokerage compensation, title and closing charges, taxes, prorations, and any agreed repairs. These expenses form part of your Atlanta home seller costs and should be estimated before you accept an offer.
A useful comparison includes the buyer's financing, appraisal and inspection contingencies, proposed closing date, earnest money, and likelihood of completing the transaction. A slightly lower but more dependable offer can sometimes be the better business decision.
Residential vs. Commercial Contexts
Residential and commercial transactions both use concessions, but their structures and purposes can differ.
In a home sale, a seller might contribute toward eligible closing costs, agree to a repair credit, or fund an interest-rate buydown through an approved arrangement.
In seller concessions commercial real estate transactions, negotiations may involve tenant improvement allowances, leasing incentives, or agreed contributions toward transaction expenses.
For example, a commercial property owner might offer a tenant an allowance to customize an office or retail space. In a sale, the parties may negotiate different property-related credits or adjustments depending on the contract.
These arrangements are not interchangeable. Commercial concessions depend on the transaction structure, lease or purchase agreement, and applicable financing terms. For residential sellers, the important lesson is to evaluate every concession according to its actual cost and business purpose rather than treating it as a personal setback.
Limits and Regulations on Concessions
Lender Caps on Contributions
A key part of any Atlanta seller concession guide is understanding that seller contributions are not unlimited. The applicable cap depends on the buyer's mortgage program, occupancy, loan-to-value ratio, and lender requirements.
For conventional loans following Fannie Mae guidelines, maximum financing concessions for a principal residence or second home are generally:
- 3% when the loan-to-value ratio is greater than 90%.
- 6% when the ratio is between 75.01% and 90%.
- 9% when the ratio is 75% or less.
- 2% for investment properties, regardless of the loan-to-value ratio.
These limits are generally calculated using the lower of the sales price or appraised value. Eligible contributions also cannot exceed the borrower's actual closing costs. Certain customary seller-paid costs are treated differently under the guidelines.
Other loan programs have their own rules, so these percentages should not be applied automatically to every transaction. Seller concessions generally cannot be used to fund a buyer's down payment or satisfy minimum borrower contribution requirements under Fannie Mae guidelines.
Before agreeing to a requested amount, ask the buyer's lender to confirm what is permitted under the specific loan.
Appraisal Considerations
Increasing a home's purchase price to offset a concession can create complications. The property still needs to appraise sufficiently to support the agreed price and the lender's underwriting requirements.
For example, if a buyer offers $500,000 with a request for $10,000 in concessions, the parties should not assume that increasing the price to $510,000 will automatically make the arrangement work. A low appraisal could require renegotiation, additional cash from the buyer, or another solution permitted by the lender and contract.
The appraised value also matters when determining applicable conventional financing-concession limits. Keep the price, concession, and financing structure transparent, and coordinate with the lender before finalizing changes.
Next Steps for Atlanta Sellers
Partnering with a Negotiation Expert
Managing seller concessions in Atlanta real estate takes a clear understanding of local market conditions, contract terms, and buyer financing. An experienced Atlanta real estate agent can help you assess requests, compare competing offers, estimate net proceeds, and identify terms that may create unnecessary risk.
Your agent can also help determine whether a concession is likely to attract serious buyers or simply reduce your proceeds without improving the chances of closing.
Setting Your Strategy Upfront
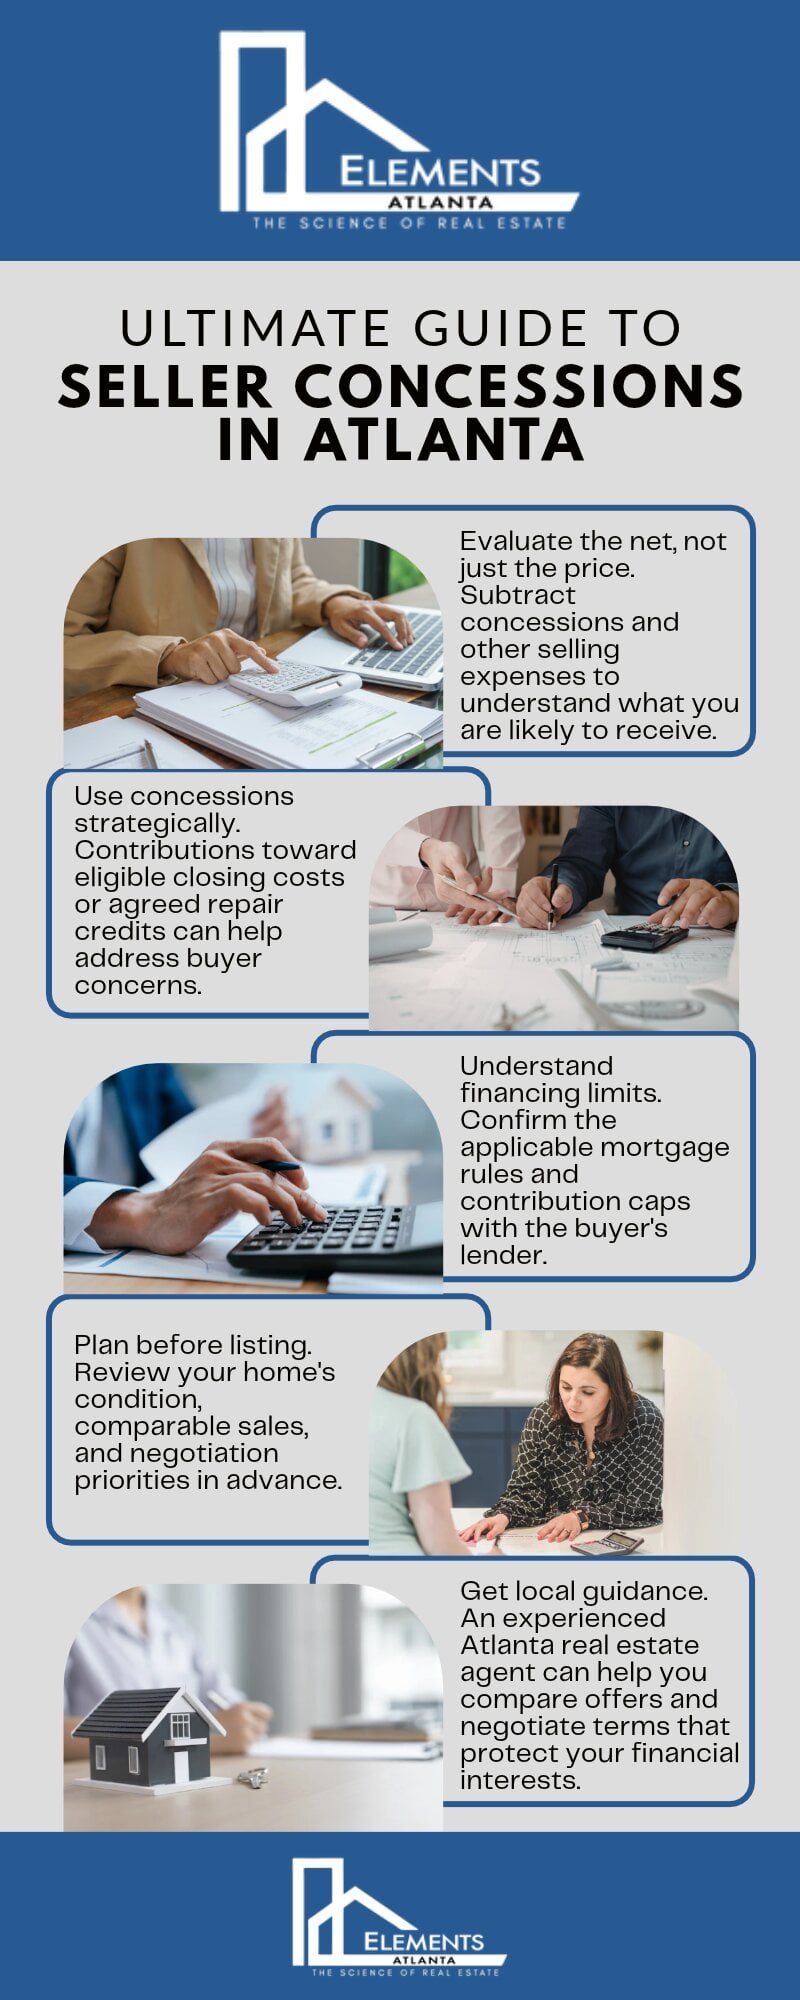
Before listing, review your home's condition, likely buyer concerns, comparable properties, and financial goals. If the roof is nearing the end of its useful life, for example, obtain an estimate for replacement and decide how much flexibility you can reasonably offer.
You might choose to complete repairs before listing, price the property to reflect its condition, or reserve room to negotiate a credit. Avoid automatically increasing your asking price to cover anticipated concessions; pricing should be supported by comparable sales and current market evidence.
A thoughtful strategy allows you to respond confidently when offers arrive instead of making rushed decisions under pressure.
Common Types of Seller Concessions Comparison Table
| Concession Type | What It Covers | Benefit to the Buyer | Impact on the Seller |
|---|---|---|---|
| Origination/Closing Costs | Eligible lender fees, title expenses, and other closing charges | Reduces the cash needed at closing | Reduces net proceeds by the agreed contribution |
| Repair Credits | Negotiated allowance for agreed inspection-related issues, where permitted | Allows the buyer to arrange repairs after closing | Avoids coordinating certain repairs but reduces proceeds |
| Property Tax Prorations | Allocates property taxes between buyer and seller according to the closing date and applicable rules | Helps ensure each party pays the appropriate share | Usually a standard closing adjustment rather than an optional incentive |
| Interest Rate Buydowns | Eligible upfront funds used to reduce the buyer's mortgage interest rate under an approved arrangement | Can lower monthly payments for a defined period or loan structure | May involve a substantial upfront contribution |
| Home Warranty | An agreed home warranty covering specified systems or appliances, subject to the policy | Provides potential protection against certain covered repair costs | Adds a relatively modest expense, depending on coverage and provider |
Maximizing Your 2026 Home Sale
Frequently Asked Questions
What are standard seller concessions in real estate for the Atlanta market?
Why would a seller consider concessions in a competitive market?
Do seller concessions in commercial real estate differ from residential sales?
How do concessions impact total Atlanta home seller costs?
Are there limits on how much a seller can give in concessions?
Should I offer a repair credit instead of fixing the home before selling it in Atlanta?
What does a typical Atlanta seller concession guide recommend when receiving multiple offers?
Check out this article next